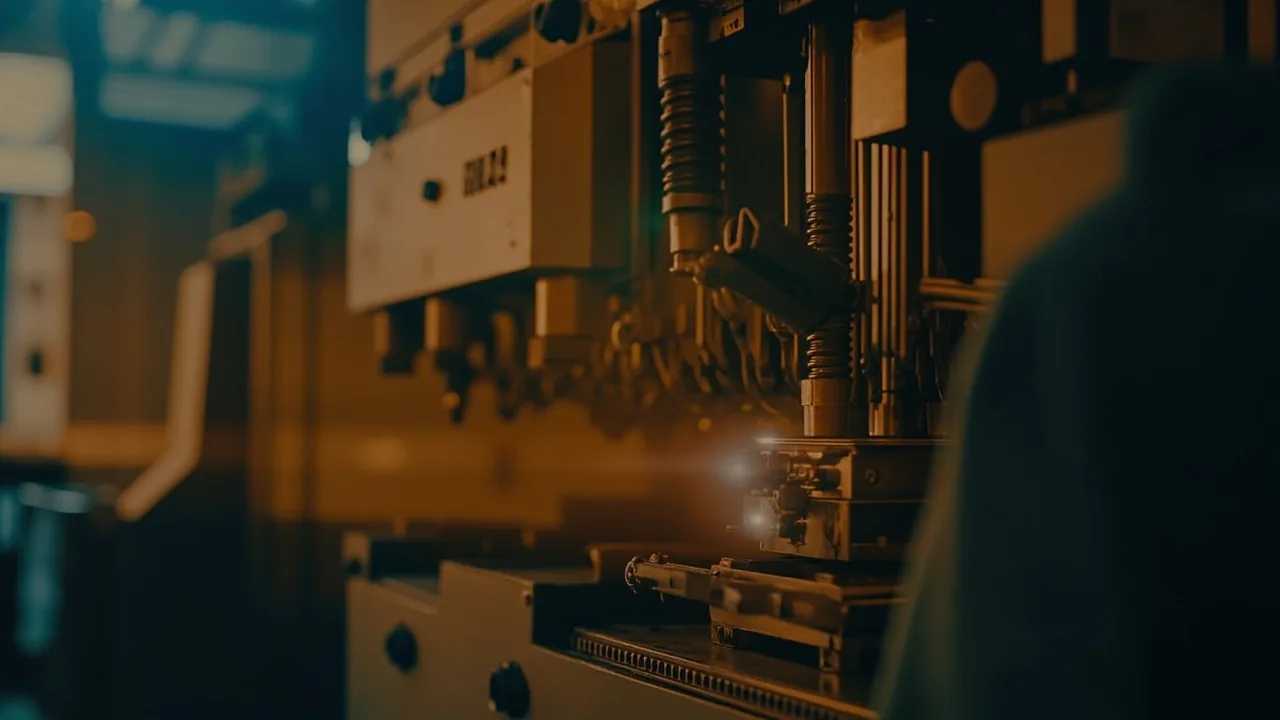
A stamping press forms sheet metal into finished parts by the thousand, and financing one lets a Canadian manufacturer grow output while keeping cash in the business.
Stamping presses are the workhorses of metal fabrication across Canada, from automotive parts in Ontario to appliance makers in Quebec. They turn out high-volume metal parts with precision, but the cash to buy one outright often puts that capability out of reach for a growing shop. Financing closes that gap and helps you stay competitive in a tough global market.
Understanding Industrial Stamping Presses
A stamping press shapes or cuts metal by driving force into a workpiece. Presses come in mechanical, hydraulic, and servo-driven types, each suited to different production work. Size and tonnage drive the price: the bigger the machine, the bigger the cheque.
Shops in automotive, aerospace, construction, and consumer goods use this machinery every day. A mid-volume C-frame mechanical press can run anywhere from $50,000 to $500,000, while a high-tonnage transfer press for complex auto body panels can top several million. At those prices, it pays to know your financing options.
Why Finance Stamping Presses Instead of Purchasing Outright
Financing versus buying outright comes down to your cash flow, your tax position, and your longer-term plan. For most Canadian manufacturers, financing beats putting a large sum of cash into a depreciating asset. It keeps working capital free for inventory, staffing, R&D, or whatever generates a faster return.
Financing also keeps you flexible. Stamping technology keeps moving: newer models are more efficient, cycle faster, and automate more. Financing lets you step up at the end of the term instead of being stuck with a dated machine.
Equipment Financing Options for Canadian Manufacturers
There are three main ways to finance a press: a lease, a loan, or a sale-leaseback. Knowing the differences helps you pick the one that fits your operation and your books.
Equipment Lease
A lease lets you run the press for a set term while making regular payments. When it ends, you can usually buy at fair market value, move up to newer technology, or return it. Leasing protects capital and gives you a predictable monthly payment that makes budgeting easier.
Equipment Loan
An equipment loan works like any business loan, with the press as collateral. You own the machine from day one, though the lender holds a security interest until it is paid off. Loans suit a shop that wants ownership and can carry a higher monthly payment than a lease.
Sale-Leaseback
A sale-leaseback is for a press you already own: you sell it to a finance company and lease it back on terms that fit. It turns the equity in equipment you already run into working capital without slowing production.
Tip for Canadian Manufacturers
When you weigh options, look at the whole cost, including interest rates, fees, and any purchase option at the end, not just the monthly figure. Some shops start with a lease to stay flexible; others prefer a loan when long-term ownership is the goal. Run your five-year projections before you lock anything in.
Benefits of Leasing Stamping Press Equipment
The main benefits of leasing a press are a fixed payment, a small initial outlay, possible off-balance-sheet treatment, and flexible terms. The fixed monthly payment makes forecasting easier. And unlike a loan, which often requires a large down payment, a lease usually asks only for the first and last payment up front.
A lease may also get off-balance-sheet treatment, depending on the structure and your accounting, which can improve the ratios lenders and investors watch. For a growing shop applying for other credit, that matters.
Terms can also be matched to your production and revenue. If demand swings with the seasons, stepped or flexible payment schedules can line the cost up with actual cash flow instead of straining you through the slow months.
Canadian Tax Advantages for Equipment Financing
Tax treatment under the Income Tax Act is one of the strongest reasons to finance. Operating lease payments and the interest on a loan may be deducted as business expenses, which lowers taxable income while you keep cash for operations. The Canada Revenue Agency's guidance on leasing costs says to “Deduct the lease payments incurred in the year for property used in your business.” (CRA) Your accountant can help you structure the deal to get the most from the deductions.
The CRA also lets you claim capital cost allowance on eligible equipment you own or finance with a loan or capital lease, and some manufacturing equipment qualifies for accelerated depreciation, with bigger deductions in the early years. On an operating lease, the lessor usually owns the machine and claims those deductions, passing some of the benefit back as a lower payment.
Provincial tax matters too. Ottawa sets the capital cost allowance framework, but how provincial sales tax treats a purchase versus a lease changes the math. In B.C., Saskatchewan, or Manitoba, where PST applies, compare the full cost of buying against leasing before you decide.
Qualifying for Equipment Financing in Canada
Qualifying for equipment financing depends on more than a credit score. The lender treats the press itself as collateral, which usually means better terms than an unsecured loan. The machine's age, condition, and resale value all factor into the risk assessment.
Your financial history counts too: revenue consistency, profit trend, and what you already owe. Most providers want you to have been operating for a minimum period, often six months to two years, though some specialize in newer shops with a strong plan and a down payment.
You will need to provide financial statements, bank statements, and the specifics of the machine you want. Have your vendor quotes and specifications ready and approval moves faster. Many Canadian providers, Equipment Leasing Canada included, can decide within days on a complete file.
The Equipment Financing Application Process
The application process runs from choosing the machine to delivery, and knowing the steps helps you avoid delays:
- Choose the machine. Pin down what you need and get quotes or invoices from suppliers.
- Apply. Submit an application covering the equipment, your business, and the structure you prefer.
- Review the proposal. The lender comes back with the amount, the rate or payments, the term, and any conditions. Compare total cost across structures if you have choices.
- Accept. The lender coordinates with the vendor, usually paying the supplier directly rather than you.
Because the vendor is paid directly, the machine is delivered and installed before your payments start, which protects both sides. Application to delivery often takes two to four weeks, though a bigger, more complex deal can take longer.
Making the Right Equipment Financing Decision
The right financing decision balances your production needs against your wider strategy. Weigh how the payment fits your operating budget, whether you want eventual ownership or the freedom to upgrade, and how the deal affects your tax position.
For many manufacturers it comes down to lease versus loan on total cost and strategy. A lease means lower payments and flexibility, but no ownership at the end unless you exercise a buyout. A loan builds equity but costs more monthly and puts the machine on your books from the start.
An experienced provider can help you see all the options and what they mean. Before you sign anything, review your statements, project how hard you will run the machine over the term, and run best-case, worst-case, and likely scenarios. That puts you in a position to negotiate and pick the structure that serves you long term.
Canadian manufacturing keeps shifting toward automation, efficiency, and fast response to demand. Financing a press keeps you current on technology while protecting working capital, so you can pivot quickly when the market moves.
Ready to finance a stamping press? Apply for equipment financing or estimate your monthly payment.
Frequently Asked Questions
What credit score is needed to finance industrial stamping presses in Canada?
It depends on more than your personal score. Lenders also weigh your revenue, time in business, and the machine itself. A shop with solid revenue and a track record can qualify even with imperfect personal credit, because the press serves as collateral, which loosens the criteria compared with a bank loan.
Can I finance used stamping presses for my Canadian manufacturing business?
Yes. Many providers finance pre-owned presses. A used machine means more due diligence on condition, maintenance history, and remaining life, and some lenders set age limits. Done right, used equipment can save money while still giving you the production you need.
How long can I finance a stamping press in Canada?
Usually two to seven years, depending on the machine's value, your preference, and the lender. A shorter term means higher payments but less total interest; a longer one lowers the monthly payment but costs more overall. Some shops match the term to the press's productive life, while others go by what the monthly payment allows.
What documentation is required to apply for stamping press financing?
Standard paperwork includes a couple of years of financial statements, bank statements showing cash flow, your incorporation or registration documents, ID for the principals, and vendor quotes or invoices. Having it ready speeds up approval.
Are there tax benefits for financing versus purchasing stamping presses outright?
Yes, either way. Operating lease payments are generally deductible as business expenses, lowering taxable income. On a purchase, capital cost allowance gives deductions over time by asset class. Which works out better depends on your structure, income, and the financing you choose, so check with a Canadian tax professional.
Share this article
Need Equipment?
Get approved for equipment financing in as little as 24 hours. No obligation application.
Get a Free QuoteOr call us directly
1-833-924-9554